The retail landscape has undergone a tectonic shift where the digital storefront now acts as the front door to the physical shop, creating a symbiotic relationship that redefines traditional shopping metrics. Contemporary retail is no longer defined by a binary choice between online and offline platforms but rather by a unified strategy that leverages each to strengthen the other. This transformation was particularly evident in the apparel and footwear sectors during the fiscal cycles of 2026 and 2027, where a stores-first philosophy became the primary driver of sustainable revenue. Leading organizations recognized that physical locations provided more than just shelf space; they functioned as logistics centers, brand showrooms, and sensory experience hubs that digital-only competitors struggled to replicate.
The Modern Retail Ecosystem: Integrating Physical and Digital Realms
Siloed channels have dissolved in favor of a cohesive model where data flows freely between the mobile app and the store aisle. This integration allows retailers to view the consumer journey as a continuous loop, where an initial search on a smartphone often culminates in a physical visit. By removing the friction between these touchpoints, companies ensure that every digital interaction serves as a potential catalyst for in-store foot traffic. The ability to check local stock levels in real time has turned casual browsing into a purposeful mission for many consumers.
The significance of the stores-first philosophy has become a hallmark for specialty retailers such as Boot Barn. Their strategic focus centers on utilizing over 550 physical locations as the backbone of their fulfillment network, rather than relying solely on centralized warehouses. This approach allows the brand to offer a broader inventory assortment online while ensuring that the most efficient shipping point remains the local store closest to the customer. This model has proven resilient even as digital demand continues to fluctuate.
Key market players like American Eagle and Deckers Outdoor Corporation have mirrored this trend by optimizing their footprints to support omnichannel demand. Technological influences play a decisive role, as sophisticated inventory management systems provide real-time visibility across all locations. These data-driven systems ensure that stock is positioned where it is most likely to sell, minimizing markdowns and maximizing the efficiency of every square foot of retail space.
The Evolution of Consumer Engagement and Market Performance
Emerging Trends in Hybrid Fulfillment and Brand Discovery
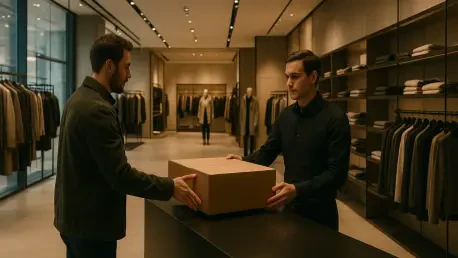
The rise of “Buy Online, Pick Up In Store” (BOPIS) and ship-to-store services has fundamentally altered consumer expectations for speed and convenience. These services act as primary traffic drivers, effectively bringing the digital customer into the physical environment where incremental sales are more likely to occur. Retailers have observed that once a customer enters the store to retrieve an online order, the likelihood of additional impulse purchases increases significantly.
Digital platforms are increasingly acting as marketing funnels rather than standalone revenue streams. Websites and social media channels serve to build brand equity and inform consumers, but the final conversion often happens in a physical showroom where the product can be touched and tested. This shift toward using physical stores as sensory destinations helps brands stand out in a saturated digital market, as the tangible experience fosters a deeper emotional connection with the product.
Evolving consumer behaviors favor immediate gratification, which is most effectively satisfied through store-based fulfillment. Whether it is a last-minute outfit for an event or a specialized piece of footwear, the proximity of store inventory to the urban consumer provides a competitive edge over e-commerce giants that rely on multi-day shipping. This proximity allows retailers to capture demand at the exact moment of intent.
Market Data and Performance Projections for Omnichannel Leaders
Analysis of same-store sales growth across key retailers reveals that omnichannel leaders are outperforming their single-channel peers. For instance, Boot Barn reported a 4.7% increase in same-store sales during early 2027, supported by a double-digit rise in e-commerce comparable sales. This growth was not merely a result of higher transaction volumes but was heavily influenced by a 3% increase in Average Unit Retail (AUR), suggesting that consumers are willing to pay more for brands that offer a seamless shopping experience.
Projections for Direct-to-Consumer (DTC) channel expansion indicate a robust growth trajectory from 2026 to 2028. Deckers Outdoor Corporation has seen its HOKA brand surge by 17% in the DTC segment, prompting the expansion of global mono-brand physical locations to anchor its brand identity. These future growth indicators are particularly strong during seasonal shopping peaks, where the combination of high-volume digital traffic and robust store-based fulfillment capabilities maximizes revenue capture.
Navigating Operational and Logistics Hurdles
Addressing the complexities of ship-from-store logistics requires a high degree of inventory accuracy that many traditional retailers are still working to achieve. When a store doubles as a warehouse, the margin for error in stock counting disappears, as a single misplaced item can lead to a cancelled online order and a frustrated customer. Maintaining this precision involves significant investments in radio-frequency identification (RFID) technology and rigorous staff training to ensure every unit is accounted for in real time.
Another significant hurdle is the difficulty of direct attribution for untracked in-store purchases that were influenced by digital touchpoints. A consumer might browse an exclusive-brand website for weeks before finally deciding to buy in person, making it hard for marketing teams to justify digital spending based on traditional metrics. Overcoming this lack of visibility requires more integrated loyalty programs that can track customer behavior across both digital and physical realms without being overly intrusive.
Managing the high costs of store-based fulfillment remains a constant challenge compared to centralized warehouse distribution. While shipping from a store is often faster, the labor costs associated with picking, packing, and processing individual orders in a retail environment can erode merchandise margins. Retailers must balance these costs against the savings found in reduced shipping distances and lower return rates, as in-store interactions often ensure the customer leaves with the correct size and style.
Governance, Compliance, and Data Security Standards
The role of data privacy regulations is paramount in managing consumer information across integrated touchpoints. As retailers collect more data to personalize the omnichannel experience, they must comply with evolving standards that protect customer identities and financial details. Ensuring that a customer’s digital profile is handled securely when they transition to an in-store transaction requires robust encryption and a transparent approach to data usage.
Security measures for integrated payment systems are becoming more complex as retailers accept a wider variety of digital wallets and contactless payments. These systems must be unified across the entire fleet of stores to prevent vulnerabilities that could lead to data breaches. Regular audits and compliance with payment card industry standards are necessary to maintain consumer trust, especially when store associates are handling sensitive information via mobile point-of-sale devices.
Compliance with retail labor standards and physical store safety regulations is also a critical factor during periods of rapid expansion. As stores take on more fulfillment responsibilities, the workload for associates shifts from pure customer service to a hybrid of service and logistics. Ensuring that these employees are trained safely and that store layouts are optimized for both foot traffic and packing activities is essential for maintaining operational integrity and meeting regulatory requirements.
The Future of Retail: Innovation and Disruptive Growth
Sophisticated data analytics are now being used to deepen consumer connections by predicting demand with unprecedented accuracy. By analyzing local trends and digital browsing patterns, retailers can pre-position stock in specific neighborhoods even before an order is placed. This proactive approach to inventory reduces shipping times and ensures that the physical store remains the most relevant node in the supply chain for the local community.
Potential market disruptors include AI-driven personalized shopping assistants and augmented reality showrooms that bridge the gap between the screen and the shelf. These technologies allow customers to visualize products in their own homes or virtually try on apparel before visiting a store to make a final purchase. As these tools become more mainstream, the physical store will evolve into a high-tech engagement center where technology enhances the human interaction rather than replacing it.
The expansion of mono-brand physical locations will continue to anchor global brand identities, especially for footwear companies looking to establish a premium presence. These flagship stores serve as the ultimate expression of the brand, providing a controlled environment where the narrative is not diluted by third-party retailers. As global economic conditions shift, these hubs will remain vital for maintaining a direct connection with shifting demographics that value brand authenticity.
Strategic Outlook for the Omnichannel Retail Landscape
The comprehensive analysis indicated that the synthesis of digital engagement and physical brand experiences created a more resilient retail model. It was observed that retailers who prioritized the store as a fulfillment hub managed to navigate the volatility of shipping costs more effectively than those who relied on a centralized approach. The findings suggested that the most successful firms were those that viewed their physical footprint as a strategic asset rather than a legacy liability, allowing them to capture demand across all possible customer touchpoints.
It was recommended that investors and retailers continued to prioritize investments in integrated ecosystems that supported both speed and experience. The strategy of using digital platforms as a funnel for store traffic proved to be a sustainable way to increase average unit retail values and maintain healthy margins. Ultimately, the transition toward a unified retail environment demonstrated that the physical store remained the heartbeat of the industry, provided it was supported by a robust and intelligent digital infrastructure.