Market competition in the credit sector is intended to drive innovation in encryption and fraud prevention through a competitive race to the top. As the United States moves through the 2026 economic landscape, the Credit Card Competition Act (CCCA) has emerged as a pivotal mechanism for restructuring the domestic payment ecosystem. Currently, the market is characterized by a significant duopoly held by Visa and Mastercard, which collectively control a vast majority of credit card processing. This lack of alternative routing allows large card-issuing banks to set non-negotiable swipe fees that merchants must pay on nearly every transaction. The National Retail Federation has highlighted the contrast between the thin 2% profit margins of the retail sector and the robust margins enjoyed by financial institutions. By mandating that large banks provide at least two unaffiliated networks for routing, the act seeks to inject transparency and cost-efficiency into a system that has long operated without meaningful competition.
Economic Impacts on Consumers and Businesses
Retail Pricing and Market Dynamics
A central debate involves whether retailers will pass savings along to consumers or simply absorb them to bolster their own bottom lines. Historical data from the 2011 debit card swipe fee reform provides a strong empirical foundation for the argument that competition drives price reductions. During the period following that reform, many retailers successfully utilized the reduction in transaction overhead to mitigate rising wholesale costs in other operational areas, such as logistics and raw materials. Between 2011 and 2016, while wholesale prices rose by approximately 9.4%, consumer prices only saw a 4.3% increase, indicating that merchants absorbed a significant portion of those inflationary pressures. This historical precedent suggests that the hyper-competitive nature of the American retail industry naturally compels businesses to pass on operational savings to maintain their market share and appeal to price-sensitive shoppers in a difficult economy.
The ongoing burden of swipe fees essentially functions as a hidden tax on every purchase, impacting consumers regardless of whether they choose to pay with cash, debit, or credit. These fees are baked into the shelf price of everyday goods, meaning that a gallon of milk or a tank of gasoline is priced higher to account for the processing costs imposed by the major card networks. By introducing alternative routing options, the Credit Card Competition Act aims to remove these artificial inflationary pressures, potentially saving American households billions of dollars annually. When transaction costs are lowered through market forces, the overall cost of doing business decreases, allowing for more stable pricing structures across the board. This shift is particularly important in an environment where supply chain volatility remains a factor. Lowering the friction of payments ensures that the value of the dollar is maximized for the average consumer while reducing the overhead for providers.
Support for Small Business Owners
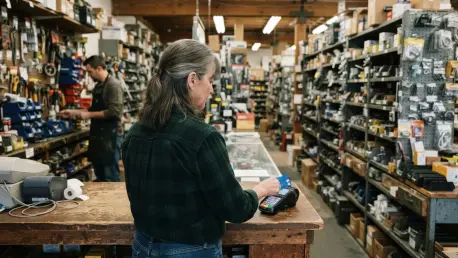
Small business owners often face the most significant challenges under the current payment processing regime because they lack the transactional volume required to negotiate favorable rates. Unlike massive international corporations that can leverage their scale to secure lower fees, independent local merchants are typically forced to accept a take-it-or-leave-it fee structure from dominant networks. These fees represent a massive, non-negotiable overhead expense that can equate to a significant percentage of a small shop’s total revenue. For many local hardware stores, family-owned restaurants, and boutique shops, the high cost of credit card processing limits their ability to compete with larger entities. The Credit Card Competition Act seeks to rectify this imbalance by requiring that alternative, lower-cost networks be available for every transaction. This would allow small business owners to choose the most efficient routing path, effectively leveling the playing field.
Furthermore, the economic relief provided to small businesses by reducing swipe fees has a profound ripple effect on local economies and community development. When a local merchant is able to retain more of their hard-earned revenue, that capital is frequently reinvested back into the business in the form of employee wage increases, new equipment purchases, or expanded inventory. This creates a more vibrant and diverse economic environment, as independent businesses are better equipped to withstand financial fluctuations and invest in their local workforces. By breaking the monopoly on credit routing, the legislation fosters a system where local entrepreneurs can thrive based on the quality of their services rather than being drained by unavoidable financial intermediaries. The ability to choose a more affordable processing network empowers these business owners to focus on innovation and customer service, which are the true drivers of long-term economic growth at the community level.
Loyalty Programs and Financial Security
The Future of Credit Card Rewards
Concerns regarding the potential disappearance of credit card rewards programs often dominate the public discourse when discussing payment reforms. However, an analysis of banking industry financial data reveals a substantial disparity between the revenue generated from swipe fees and the actual cost of funding these loyalty programs. In the current year, major financial institutions collected nearly $190 billion in swipe fees while paying out approximately $47.5 billion in consumer rewards and cash-back incentives. This suggests that even if swipe fees were significantly reduced through increased competition, banks would still retain over $140 billion in revenue from those fees alone. This figure does not even account for the massive earnings derived from interest payments, late fees, and annual membership charges. Given this immense profit cushion, it is highly likely that rewards programs will remain a fixture of the financial landscape as a marketing tool for banks.
International precedents further support the idea that credit card rewards can successfully coexist with lower transaction fees and more competitive market structures. In regions such as the European Union and Australia, where swipe fees have been capped at a fraction of the current U.S. levels for years, financial institutions continue to offer robust loyalty and incentive programs. These banks have adapted by finding other efficiencies or recognizing that the value of customer data and long-term lending relationships outweighs the costs of providing rewards. In a competitive lending market, banks must differentiate themselves to win over consumers, and rewards programs remain one of the most effective ways to achieve this goal. Therefore, the narrative that competition will lead to the end of cash-back perks or travel points appears to be an oversimplification of how modern financial services operate. Banks are incentivized to maintain these programs to prevent losing their cardholders to competitors.
Enhancing Transaction Safety and Innovation
There is a persistent misconception that smaller, independent payment networks lack the security infrastructure and technological sophistication of the dominant card giants. On the contrary, data from the Federal Reserve has indicated that independent debit networks often exhibit fraud rates that are significantly lower than those associated with Visa and Mastercard. The United States currently experiences a disproportionate share of global credit card fraud, accounting for roughly 42% of all fraud incidents despite only processing about 26% of the world’s total transaction volume. This suggests that the current concentrated market structure has not effectively mitigated security risks. By mandating the inclusion of alternative networks, the Credit Card Competition Act encourages a more diverse array of security protocols to be deployed across the payment ecosystem. A variety of processing options forces all players to enhance their encryption systems to remain trusted by merchants.
The implementation of competitive routing options effectively catalyzed a shift toward more advanced security technologies such as biometric authentication and enhanced tokenization. As networks vied for the preference of merchants, they prioritized the development of superior fraud detection algorithms to minimize the costs associated with transactional disputes. This transition demonstrated that a diversified marketplace was more resilient than a centralized one, as it allowed for the rapid adoption of emerging security standards. Moving forward, businesses looked toward adopting multi-network integration strategies to further optimize their payment overhead and improve customer checkout experiences. Policymakers monitored the resulting economic shifts, observing how the reduction in swipe fees translated into increased capital availability for infrastructure investments and localized hiring initiatives. This legislative change provided a clear roadmap for future financial modernizations.