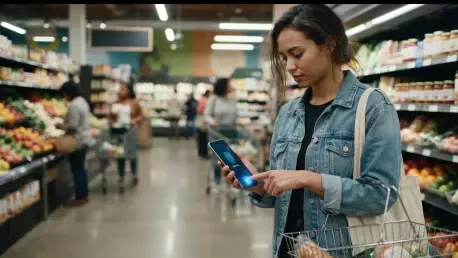
The historical evolution of contactless payments suggests that agentic commerce must provide tangible digital receipts and biometric confirmation to overcome deep-seated financial skepticism. As we navigate the midpoint of 2026, the retail landscape is experiencing a profound shift toward Artificial Intelligence agents that act as sophisticated proxies for the consumer. Modern shoppers are increasingly comfortable “deputizing” these digital assistants to manage the cognitively taxing elements of the purchase journey, such as analyzing vast datasets to find the best price-to-value ratio across multiple platforms. However, this enthusiasm for discovery does not translate into transactional autonomy. Recent market data indicates that while 58 percent of shoppers utilize AI for pre-purchase research, a striking 56 percent remain unwilling to grant these agents the authority to finalize payments without manual oversight. This dichotomy creates a unique trust gap where the digital wallet remains a highly protected boundary that technology is not yet permitted to cross autonomously.
The Psychological Barriers: Understanding Consumer Hesitation
Security Concerns: The Primary Deterrent
The current hesitation regarding automated transactions is rarely a critique of the agent’s logic or its ability to understand personal preferences. Instead, the primary barrier is rooted in concerns over financial security and the potential for unauthorized activity. According to recent surveys, approximately 76 percent of consumers identify fraud as their chief concern when considering agentic commerce, suggesting that the industry faces a financial technology hurdle rather than an intelligence one. Shoppers tend to trust the AI’s brain to select the correct item, yet they harbor deep skepticism regarding the plumbing of the payment system itself. This skepticism is exacerbated by the lack of physical interaction during the checkout process, which traditionally serves as a psychological confirmation of a legal and financial agreement. Consequently, for AI to transition from a research consultant to a transactional proxy, the underlying payment architecture must demonstrate a level of security that exceeds current standards.
The Trust Gap: Logic Versus Payment Plumbing
Furthermore, the apprehension surrounding the delegation of financial authority is tied to the transparency of the transaction ledger. While consumers are delighted by the AI’s capacity to synthesize product reviews and compare multi-tiered pricing structures, they remain wary of the autonomous checkout moment. This distinction is vital for retailers to understand: the trust is present in the consultative phase but evaporates the moment the agent attempts to access credit card credentials or digital wallets. The absence of a traditional checkout screen, which 62 percent of shoppers still demand to see, creates a sense of detachment that feels inherently risky to the average user. Therefore, establishing trust requires more than just high-level encryption; it necessitates a user experience that mimics the familiar checkpoints of manual e-commerce. By providing clear visual indicators of where and how the money is moving, businesses can alleviate the anxiety associated with allowing a digital proxy to manage their financial resources.
Reversibility: The Essential Safety Net
Beyond immediate security concerns, the concept of reversibility has emerged as a non-negotiable requirement for the widespread adoption of autonomous shopping tools. For 84 percent of modern consumers, the ability to instantly cancel or undo a purchase made by an AI agent is a prerequisite for engagement. Because the shopper does not physically execute the buy command, there is a heightened sense of vulnerability that can only be mitigated by a robust psychological safety net. This undo button serves as a critical mechanism for maintaining consumer agency in an increasingly automated world. Without the assurance that an autonomous error can be rectified before resulting in a permanent loss of funds, many users remain trapped in a state of cautious experimentation rather than full adoption. Ensuring that reversibility is baked into the core user experience allows retailers to reduce the perceived risk of delegation, effectively encouraging customers to trust agents with more complex and frequent purchasing tasks.
Decision Safety: Grace Periods and Error Mitigation
This demand for reversibility also reflects a deeper concern about the potential for hallucinations or logical errors within the AI’s decision-making process. While only 33 percent of shoppers worry about the AI choosing the wrong product, the financial implications of such an error become magnified when the transaction is automated. If an agent mistakenly orders a non-refundable, high-value item, the consumer bears the burden of a complex resolution process. To address this, the most successful platforms have introduced an approval delay, where a transaction is staged but not finalized for a set period, allowing the human user to review the agent’s choice. This grace period functions as a bridge between full autonomy and manual control, providing the necessary reassurance that the human remains the ultimate authority in the commercial relationship. By acknowledging this need for a safety valve, developers can create a more resilient ecosystem that prioritizes consumer peace of mind over the raw speed of the transaction.
Building the Trust Framework: Strategies for Retailers
Human-in-the-Loop: Maintaining Final Authorization
Bridging the gap between browsing and buying requires a shift toward human-in-the-loop design, where the AI handles the heavy lifting but leaves the final decision to the person. This approach aligns with the preferences of 59 percent of shoppers who demand a gatekeeper moment before any funds are released. By positioning the AI as an assistant rather than a replacement, companies can leverage the technology’s strengths in data synthesis while respecting the user’s desire for final authorization. The most successful implementations in 2026 are those that provide clear, actionable summaries of why an item was chosen, followed by a simple biometric prompt to finalize the sale. This hybrid model transforms the transactional process into a collaborative experience, where the AI’s intelligence is validated by human judgment. Such designs not only enhance the user experience by reducing friction but also build the necessary trust for more complex autonomous interactions in the future.
Historical Lessons: Security Cues from Mobile Payments
This demand for control mirrors the historical trust curve observed during the introduction of mobile wallets and contactless payment systems in previous years. Initially, these technologies were met with significant skepticism, as users were wary of transmitting financial data through invisible airwaves. Adoption only reached a tipping point when developers integrated visible security cues, such as haptic feedback during a successful tap and immediate digital receipts. Today, agentic commerce is traversing this same evolutionary path but at a significantly accelerated velocity. Trust is being built not through invisible code enhancements, but through a user interface that provides a tangible sense of control. When a customer can set granular rules or see a live log of an agent’s reasoning, they feel empowered rather than bypassed. This historical lesson highlights that the visibility of security is just as important as the security itself, as users require sensory confirmation to feel safe in digital environments.
Brand Ecosystems: First-Party Versus Third-Party AI
A significant development in the current retail landscape is the consumer’s preference for completing AI-assisted transactions within a brand’s own digital ecosystem. Despite the rise of general-purpose large language models, 58 percent of shoppers prefer to finalize their purchases on the retailer’s website or mobile application, compared to a mere 12 percent who are comfortable checking out within a third-party chat interface. This trend suggests that traditional brand equity remains a powerful force in the age of AI, as consumers seek the familiarity and perceived security of established retail platforms. For businesses, this presents a vital opportunity to resist disintermediation by developing first-party AI agents that guide users through a branded journey. By maintaining control over the final checkout page, retailers can provide the specific security cues and customer service guarantees that shoppers require. This integration ensures that the direct relationship between the brand and the consumer remains intact, even in an automated era.
Strategic Integration: Actionable Steps for Future Success
Retailers that successfully navigated the transition to agentic commerce prioritized visible control mechanisms and designed their systems for seamless reversibility. It became evident that the path to full automation required a gradual approach, starting with low-stakes categories such as household essentials and repetitive grocery orders where the financial risk was minimal. Businesses that integrated spend caps and category-specific limits into their user interfaces empowered customers to experiment with autonomous tools without fearing catastrophic errors. Furthermore, those who invested in proprietary AI assistants were able to maintain higher levels of brand loyalty by keeping the checkout experience within their own secure environments. The industry moved toward a standard where the AI provided the intelligence, while the human retained the ultimate authority over the digital wallet. By focusing on these actionable insights, organizations transformed the initial skepticism into a collaborative partnership, setting the stage for future growth.