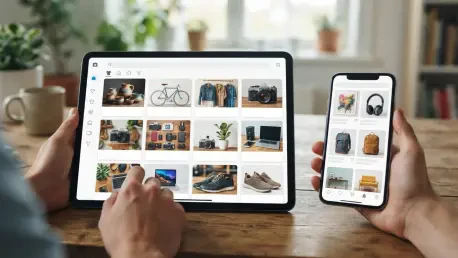
The exclusion of personal sales from the new VAT mandate ensures that casual peer-to-peer trading remains unaffected by platform tax collection. This strategic shift, set to go live in October 2027, marks a fundamental change in how the United Kingdom regulates digital commerce. By expanding the responsibility of Value Added Tax collection from individual vendors to the platforms themselves, the government aims to modernize tax recovery in an increasingly decentralized economy. This policy, confirmed during the recent budget cycles of 2026, moves beyond the previous limitations that only targeted overseas sellers. Now, the scope includes domestic businesses, placing online marketplaces at the center of tax compliance for goods located within the country at the point of sale. This transition represents a proactive effort to level the playing field between brick-and-mortar retailers and digital storefronts while ensuring that the digital economy contributes its fair share to public finances without stifling the growth of small-scale hobbyists.
Mechanism of Change: The Deemed Supply Model
The cornerstone of this regulatory update is the implementation of a deemed supply framework, which fundamentally alters the legal nature of a transaction. Under this specific model, a single sale from a third-party merchant to a consumer is treated as two distinct transactions for tax purposes. First, the seller is considered to have supplied the goods to the online marketplace as a zero-rated transaction. Second, the marketplace is then deemed to have sold those same goods directly to the final customer, making the platform responsible for charging, collecting, and remitting the correct amount of VAT to the tax authorities. This approach simplifies the collection process for the government by consolidating the tax obligations of thousands of individual sellers into a few major digital hubs. By shifting the point of accountability, the mandate reduces the administrative complexity for small businesses while providing a more transparent and manageable stream of revenue for the state treasury.
Applying these rules requires a nuanced approach to the various types of sellers currently operating in the British market. For businesses already registered for VAT, the online marketplace will account for the tax on all transactions regardless of the total sale value. However, to protect smaller entrepreneurs and startups that are not yet VAT-registered, the government introduced a Minimum Platform Threshold of £90,000. Under this provision, a marketplace only assumes VAT liability once a specific seller’s annual turnover on that particular platform exceeds this financial benchmark. It is critical for operators to recognize that this threshold is platform-specific and operates independently of a business’s legal obligation to register with the tax office if its total sales across all channels exceed the national limit. This distinction ensures that the burden of tax collection only shifts to the platform when a seller reaches a significant scale, thereby maintaining a competitive landscape for newcomers.
Operational Impacts and Strategic Compliance
The transition toward this expanded mandate necessitates a significant overhaul of the digital infrastructure currently utilized by many hosting providers. Online marketplaces are now tasked with developing and integrating sophisticated data verification systems capable of distinguishing between commercial business accounts and casual personal users in real time. These platforms must also implement robust tracking mechanisms to monitor cumulative sales figures against the new threshold to ensure they trigger VAT accounting at the precise moment required by law. Beyond simple arithmetic, the platforms must verify the VAT registration status of their users through official government databases to ensure the correct application of the deemed supply rules. This requirement introduces a layer of ongoing administrative maintenance, as statuses can change throughout the fiscal year. Failure to maintain accurate records could result in significant financial penalties, making the reliability of these automated systems a top priority for corporate legal and technical teams.
In an effort to support environmental sustainability and economic fluidity, the government specifically excluded certain categories of goods and transactions from the new VAT mandate. Most notably, transactions involving second-hand and refurbished items remain outside the scope of the deemed supply rules to preserve the integrity of the existing VAT margin scheme. This decision prevents the occurrence of double taxation, which would otherwise occur if full VAT were applied to items that had already been taxed at their original point of sale. By maintaining these carve-outs, the policy ensures that businesses dedicated to the circular economy—such as those selling used electronics or vintage clothing—do not face a sudden reduction in profit margins that could lead to higher prices for consumers. Additionally, the focus remains strictly on retail or consumer-facing transactions, leaving business-to-business sales largely unaffected by these specific platform-level changes. This targeted approach aims to close the tax gap without disrupting specialized market sectors.
The path forward required online marketplaces to initiate comprehensive audits of their current seller verification processes and tax reporting frameworks. To successfully navigate the 2027 implementation, platforms prioritized the development of clear communication channels to inform their vendors about the upcoming threshold requirements and registration protocols. Government agencies pledged to provide detailed secondary legislation and instructional guidance to facilitate a smoother transition for the digital sector. Stakeholders also recognized the importance of monitoring the effectiveness of the Minimum Platform Threshold, as future adjustments remained a possibility based on the evolving economic landscape. By addressing these compliance needs early, the industry moved toward a more equitable system that balanced the needs of small-scale entrepreneurs with the necessity of robust tax collection. These proactive measures ultimately strengthened the stability of the digital marketplace while ensuring that all participants contributed fairly to the economy through standardized fiscal practices.